Involving Family In A Reverse Mortgage Decision
How To Involve Family And Advisors In A Reverse Mortgage Decision, Without The Pressure
A reverse mortgage is rarely a decision made in complete isolation. Many homeowners want their adult children, a trusted friend, or a Power of Attorney involved in the conversation, whether for peace of mind, a second opinion, or simply to keep everyone informed about a significant financial decision affecting the family home.
This guide looks at practical ways to bring family and professional advisors into a reverse mortgage conversation in a way that feels supportive rather than pressured, and how a good advisor should make space for that involvement rather than working around it.
Why Family Involvement Often Matters
For many homeowners considering a reverse mortgage, the family home represents more than just a financial asset, it carries memories, and often forms part of what a person hopes to eventually pass on to children or grandchildren. It makes sense that a decision involving that home would feel like one worth discussing with the people it affects.
Adult children in particular sometimes have questions or concerns about how a reverse mortgage works, occasionally based on outdated information or general misconceptions about the product. Bringing them into an informed, calm conversation directly with a specialist tends to resolve far more concerns than a homeowner trying to explain second-hand what they have learned themselves.
There can also be practical reasons for involvement, particularly where a Power of Attorney is already in place, or where family members will eventually be involved in managing the estate. Understanding the reverse mortgage terms together, upfront, tends to prevent confusion or concern arising later on.
How A Good Conversation Should Feel
A well-run reverse mortgage conversation should never feel rushed or pressured, regardless of who is in the room. My approach is to answer any questions openly, whether from the homeowner directly or from family members joining the discussion, and to give everyone the time they need to feel genuinely comfortable before any decision is made.
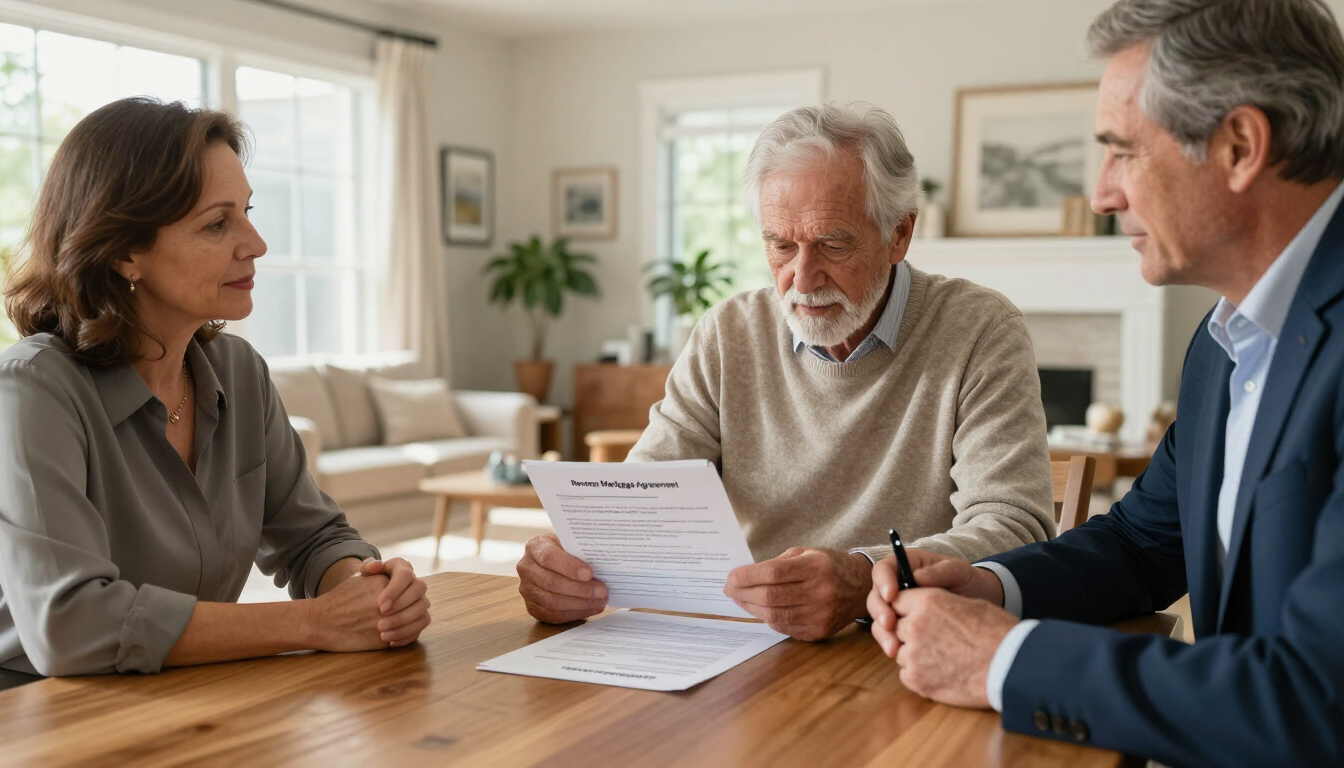
If a homeowner wants their children, Power of Attorney, or a trusted friend included in the conversation, I am happy to accommodate a meeting arranged in whatever way makes sense, whether that is everyone together at once or a series of separate conversations that come together over time.
There is no expectation that a decision needs to be made during a first meeting, or even a second one. Reverse mortgages are significant decisions, and taking the time needed, including time to consult independent legal and financial advice, is a normal and encouraged part of the process rather than something to feel rushed through.
Bringing Adult Children Into The Conversation
Inviting adult children to a conversation, even just to listen and ask their own questions, often resolves lingering concerns far more effectively than trying to relay information after the fact. Many families find this simply brings everyone onto the same page.
Working Alongside A Power Of Attorney
Where a Power of Attorney is already involved in a homeowner's affairs, including them directly in reverse mortgage discussions ensures continuity and understanding, particularly important given the long-term nature of these products.
The Role Of Independent Legal Advice
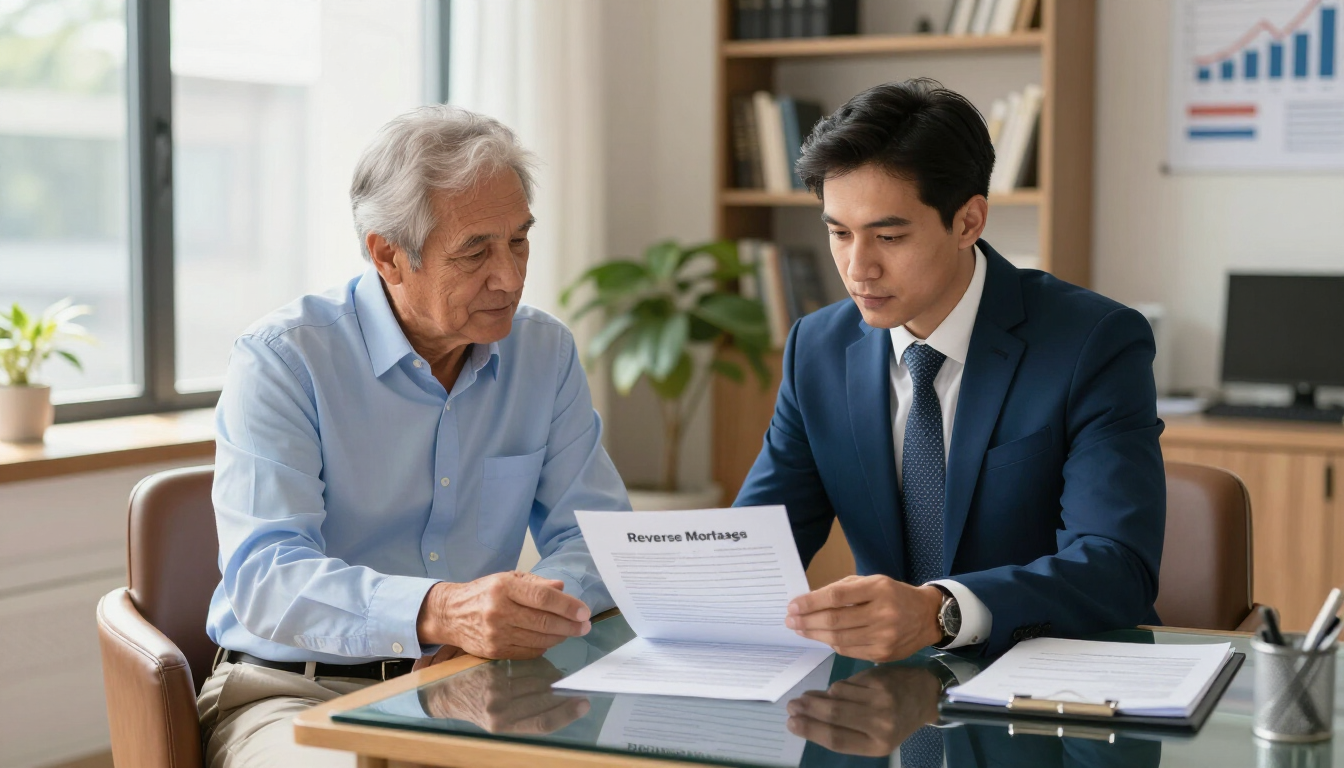
Independent legal advice is a required part of finalising a reverse mortgage in Canada, and this exists specifically to protect the homeowner by ensuring they fully understand the terms from a source entirely separate from the lender or broker arranging the mortgage.
This step should never feel like a formality to rush through. A good lawyer reviewing the paperwork will walk through the terms clearly, answer any remaining questions, and confirm that the homeowner is entering the agreement with full understanding and genuine comfort with the decision.
Involving a financial advisor, where a homeowner already works with one, is also worth considering, particularly for understanding how a reverse mortgage fits alongside other retirement income sources, investments, or estate planning considerations already in place.
Ways to build a supportive, well-informed decision-making process:
- Invite adult children or a trusted friend to join a conversation if that would help
- Take advantage of independent legal advice as a genuine opportunity to ask questions
- Loop in an existing financial advisor if one is already part of your planning
- Take as much time as needed between conversations before deciding
- Watch educational materials together as a family to build shared understanding
A Decision Made Together, At Your Own Pace
A reverse mortgage decision should never feel like something happening to a family rather than with them. Whether you want to explore this on your own first or bring loved ones in from the start, I am happy to structure conversations in whatever way genuinely helps everyone feel informed and comfortable.
Watch our video series covering myths and misunderstandings about reverse mortgages, or reach out to arrange a no-pressure conversation that includes whoever you would like involved.
FAQs
Can my children be part of the conversation about a reverse mortgage?
Absolutely. Many homeowners choose to include adult children, a Power of Attorney, or a trusted friend in these discussions, and I am happy to arrange meetings in whatever way suits your family best.
Is independent legal advice really necessary?
Yes, it is a required step in finalising a reverse mortgage in Canada, and it exists specifically to protect you by ensuring the terms are explained clearly by someone entirely separate from the lender or broker.
Will I feel pressured to decide quickly?
No. A reverse mortgage is a significant decision, and taking the time you need, including multiple conversations and independent advice, is a normal and encouraged part of the process rather than something to rush.
What if my financial advisor has questions about how this fits my retirement plan?
I am happy to speak directly with your existing financial advisor to help them understand how a reverse mortgage might fit alongside your broader retirement and estate planning.